The email address in "Contact AK: Ads and more" above will vanish from November 2018.

PRIVACY POLICY

FAKE ASSI AK71 IN HWZ.

Featured blog.

1M50 CPF millionaire in 2021!

Ever since the CPFB introduced a colorful pie chart of our CPF savings a few years ago, I would look forward to mine every year like a teena...

Past blog posts now load week by week. The old style created a problem for some as the system would load 50 blog posts each time. Hope the new style is better. Search archives in box below.

Archives

"E-book" by AK

Second "e-book".

Another free "e-book".

4th free "e-book".

Pageviews since Dec'09

Financially free and Facebook free!

Recent Comments

ASSI's Guest bloggers

Should I terminate an expensive ILP bought from a friend?

Tuesday, January 27, 2015

I received an email from a reader on an ILP she bought and I am going to share an edited version here.

Please remember that life insurance is essential but the cost of insurance should be kept low.


Hi AK,

I have recently started to read your blog and I really appreciate how you post unbiased financial advice for your readers. As such, I am really hoping you can help me with this dilemma that I have.

I have graduated last year and bought an ILP from my friend. I am investing $xxx every month into this plan for about x months now. This is a 30 year plan, and recently I'm having second thoughts about whether to continue this plan or not. 

...

I was wondering if I should discontinue the plan (because the costs are exorbitant) and invest the money myself in the OCBC BCIP, or should I just lower my contribution to $xxx a month since that is the minimum amount. Because if I cancel the plan now, I would have lost the (money) that I put in already. Please advise! Thank you in advance!

Warmest regards,


AK's reply:

Hi,

......

I wouldn't touch ILPs with a 5 feet pole myself.

Since you have come to the realisation on your own that the cost of having an ILP is exhorbitant, you might want to cut your losses instead of throwing more money into the plan. Just a thought. Not advice.

Do a comparison to see how much money you would save if you were to buy term life instead to enjoy the equivalent amount of coverage. You could invest the savings using a program like OCBC BCIP which you have identified.

I am not giving any advice. Just sharing my thoughts. :)

Best wishes,
AK


I think that this is quite a fortunate case as the reader realised quite early on how expensive the ILP actually is and is thinking of taking steps to remedy the situation quickly now. Others could be less fortunate.

Before signing on the dotted line of any proposal, it is important to read every word, sentence and paragraph carefully. Do the necessary due diligence. Then, make a well informed decision. 

If we don't understand something, make sure to clarify. If we are still confused, do not accept the proposal. Walk away.

Cultivate this habit and it will guard us against unnecessary expenses and angst in all aspects of life, not just with life insurance proposals or shopping in Sim Lim Square for the latest iPhone.

Related posts:
1. Term Life Insurance: Why buy term?
2. How much term life insurance should fresh grads have?
3. Free ILPs or Term Life Policies?
(Warning: This is highly controversial!)

Should I put money in a foreign currency fixed deposit?

Monday, January 26, 2015

Long, long time ago, I was attracted to the high interest rates of a foreign currency fixed deposit. 

Upon maturity, the interest received was not even able to cover the exchange rate loss. 

Ouch.

不好玩


No more such adventures for me. 

Once bitten, twice shy.

Even now, why do banks give higher interest rates for foreign currency fixed deposits in A$ but a lower interest rate for US$? 

Why? Why?


Clue:


Unlike a fixed deposit in S$, there is no bao jiak with fixed deposits in a foreign currency. 


Well, for us living in Singapore anyway.

Note: 
Just the view of a local frog in a local well on an island called Singapore.

Related posts:
1. Why fixed deposits?
2. Special chests for emergencies.

References:
1. Australian dollar drops to 5.5-year low after ECB move.
2. POSB 1.88% FD for 12 months.
 

One way to save money more rapidly.

Saturday, January 24, 2015

People who know me are often amazed by how quickly I am able to save money. Well, it isn't a mystery, really.

One of the things I avoid doing is dining in restaurants. How much does a meal cost in Paradise Inn or Din Tai Fung, for examples?

This doesn't mean that I don't dine in restaurants but I do it sparingly. Some might remember my fortnightly visits to Soup Restaurant, partly because I was a shareholder. Anyway, I have stopped visiting them for many moons now as I feel that the standard has dropped.

If we go to restaurants frequently, reducing the frequency meaningfully could see quite a bit of savings every month. See related post number 1 at the end of this blog post to read a family man's experience.

Feeling hungry? Just go to Old Chang Kee to get a curry puff. Doesn't cost an arm and a leg. On other days, just have simple meals at home. Sandwiches and oatmeal are easy to prepare. Porridge and noodles too.

This was what I had tonight:

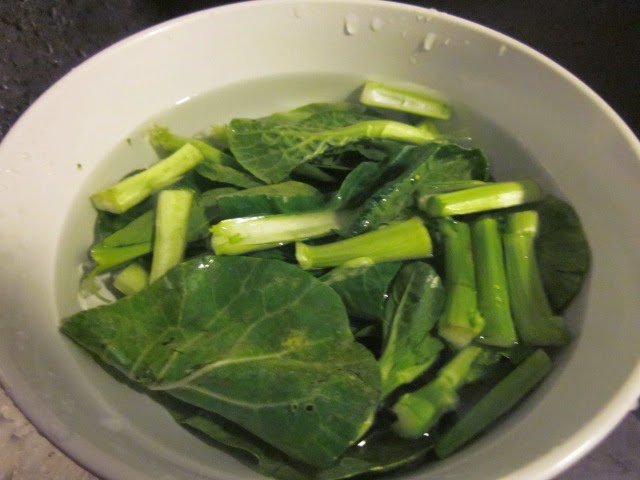
Choy sum.

Chopped and rinsed.

Time for a hot water bath.

Add some fried ikan bilis and ginger. Looks good, tastes good!

Mustn't forget to have a fruit.

Home baked chocolate chip cookie, thanks to my sis.

Avoid going to restaurants and we could save money more quickly. Feed our wallets! Burp!

Related posts:
1. How to have a comfortable retirement?
"His family used to dine in restaurants every Sunday. This is now reduced to only once a month. This helps him save more than $200 each month."
2. Rich gets richer. Poor gets poorer.
"只要功夫深,铁杆磨成针."
3. If we are not rich, don't act rich.
"Now, this may sound jaded as I have said it before many times and that is we should run our lives like we would run a business!"

A tale of two Keppels: Win, lose or draw?

Keppel Corporation is going to try to take Keppel Land private. This news came shortly after Keppel Corporation declared a generous dividend per share of 36c.

If I were a shareholder of Keppel Corporation's, I would have been elated and, then, worried by the recent string of events.

The following is taken from the comments section of my blog:


When I was asked in the last few months why did I choose to invest in SembCorp Industries instead of Keppel Corporation since both of them are blue chips in the O&M category, I said that I felt better about the former's utilities business in the current environment than the latter's real estate business. Although this latest development involves Keppel Corporation's real estate arm, quite honestly, I could never have seen this form of corporate action coming. I am just a frog in a well, after all.

Paying $4.60 a share (eventually), Keppel Corporation is not getting Keppel Land at a discount to NAV since Keppel Land's NAV/share is about there. In fact, it is going to be at a slight premium. So, there is nothing for Keppel Corporation's shareholders to rejoice about. At least, if the purchase was going to be at a discount, it might make Keppel Corporation's resulting weaker balance sheet easier to swallow.


For Keppel Corporation's action to make sense, it has to be because the management feel that Keppel Land will add value either in terms of income generation or capital appreciation in the years to come. However, near term prospects are challenging as Keppel Land is still mostly dependent on income from real estate development (property trading) although they have increased the size of their recurring income stream in recent times.

Could we see Keppel Corporation's stock price weakening next week? With a 36c dividend dangling, Mr. Market might close an eye to the eventual weaker balance sheet, for now.

Related post:
SembCorp Industries and SembCorp Marine.


Monthly Popular Blog Posts

All time ASSI most popular!


Bloggy Award